What Is Home Equity?
Home equity is the portion of your home you actually own — calculated by taking your home’s current market value and subtracting your remaining mortgage balance. Over time, as you pay down your mortgage or your home’s value rises, your equity grows. This equity can be used to secure financing for major purchases, debt consolidation, or renovations.
Home Equity Line of Credit Definition
A Home Equity Line of Credit (HELOC) is a flexible way to borrow against your home’s equity. A Home Equity Line of Credit is similar to a credit card, offering a revolving line of credit that you can access as needed. You only pay interest on the amount you use.
HELOC Explained
Here’s how a HELOC works:
- Draw Period – Typically 5–10 years, during which you can borrow, repay, and borrow again up to your credit limit.
- Repayment Period – After the draw period ends, you begin paying principal and interest until the balance is fully repaid.
- Variable Interest Rates – HELOC rates are usually tied to market conditions, so monthly payments can fluctuate.
This makes a HELOC perfect for ongoing projects like phased home improvements or tuition payments, where you may need funds at different times.
Home Equity Loan Explained
A Home Equity Loan is a fixed-term, lump-sum loan backed by your home’s equity. You receive all funds upfront and make predictable monthly payments over a set term. This is ideal for debt consolidation home equity loan strategies, large remodels, or other one-time expenses that benefit from a fixed budget and a fixed interest rate.
Difference Between HELOC and Home Equity Loan
Both a HELOC and a Home Equity Loan let you borrow against your home’s equity, but they work differently:
- HELOC – Works like a revolving credit line. You borrow as you need it, often with variable interest rates that may change over time.
- Home Equity Loan – Provides a one-time lump sum with a fixed interest rate and fixed monthly payments.
- Key Difference – HELOCs are best for ongoing or unpredictable expenses, while Home Equity Loans are best for large, planned expenses where you want a predictable payment schedule.
HELOC vs Home Equity Loan Rates
When comparing HELOC vs Home Equity Loan rates, consider:
- HELOC Rates – Usually variable, often starting lower but can adjust with market changes.
- Home Equity Loan Rates – Fixed, which gives you predictable monthly payments for the life of the loan.
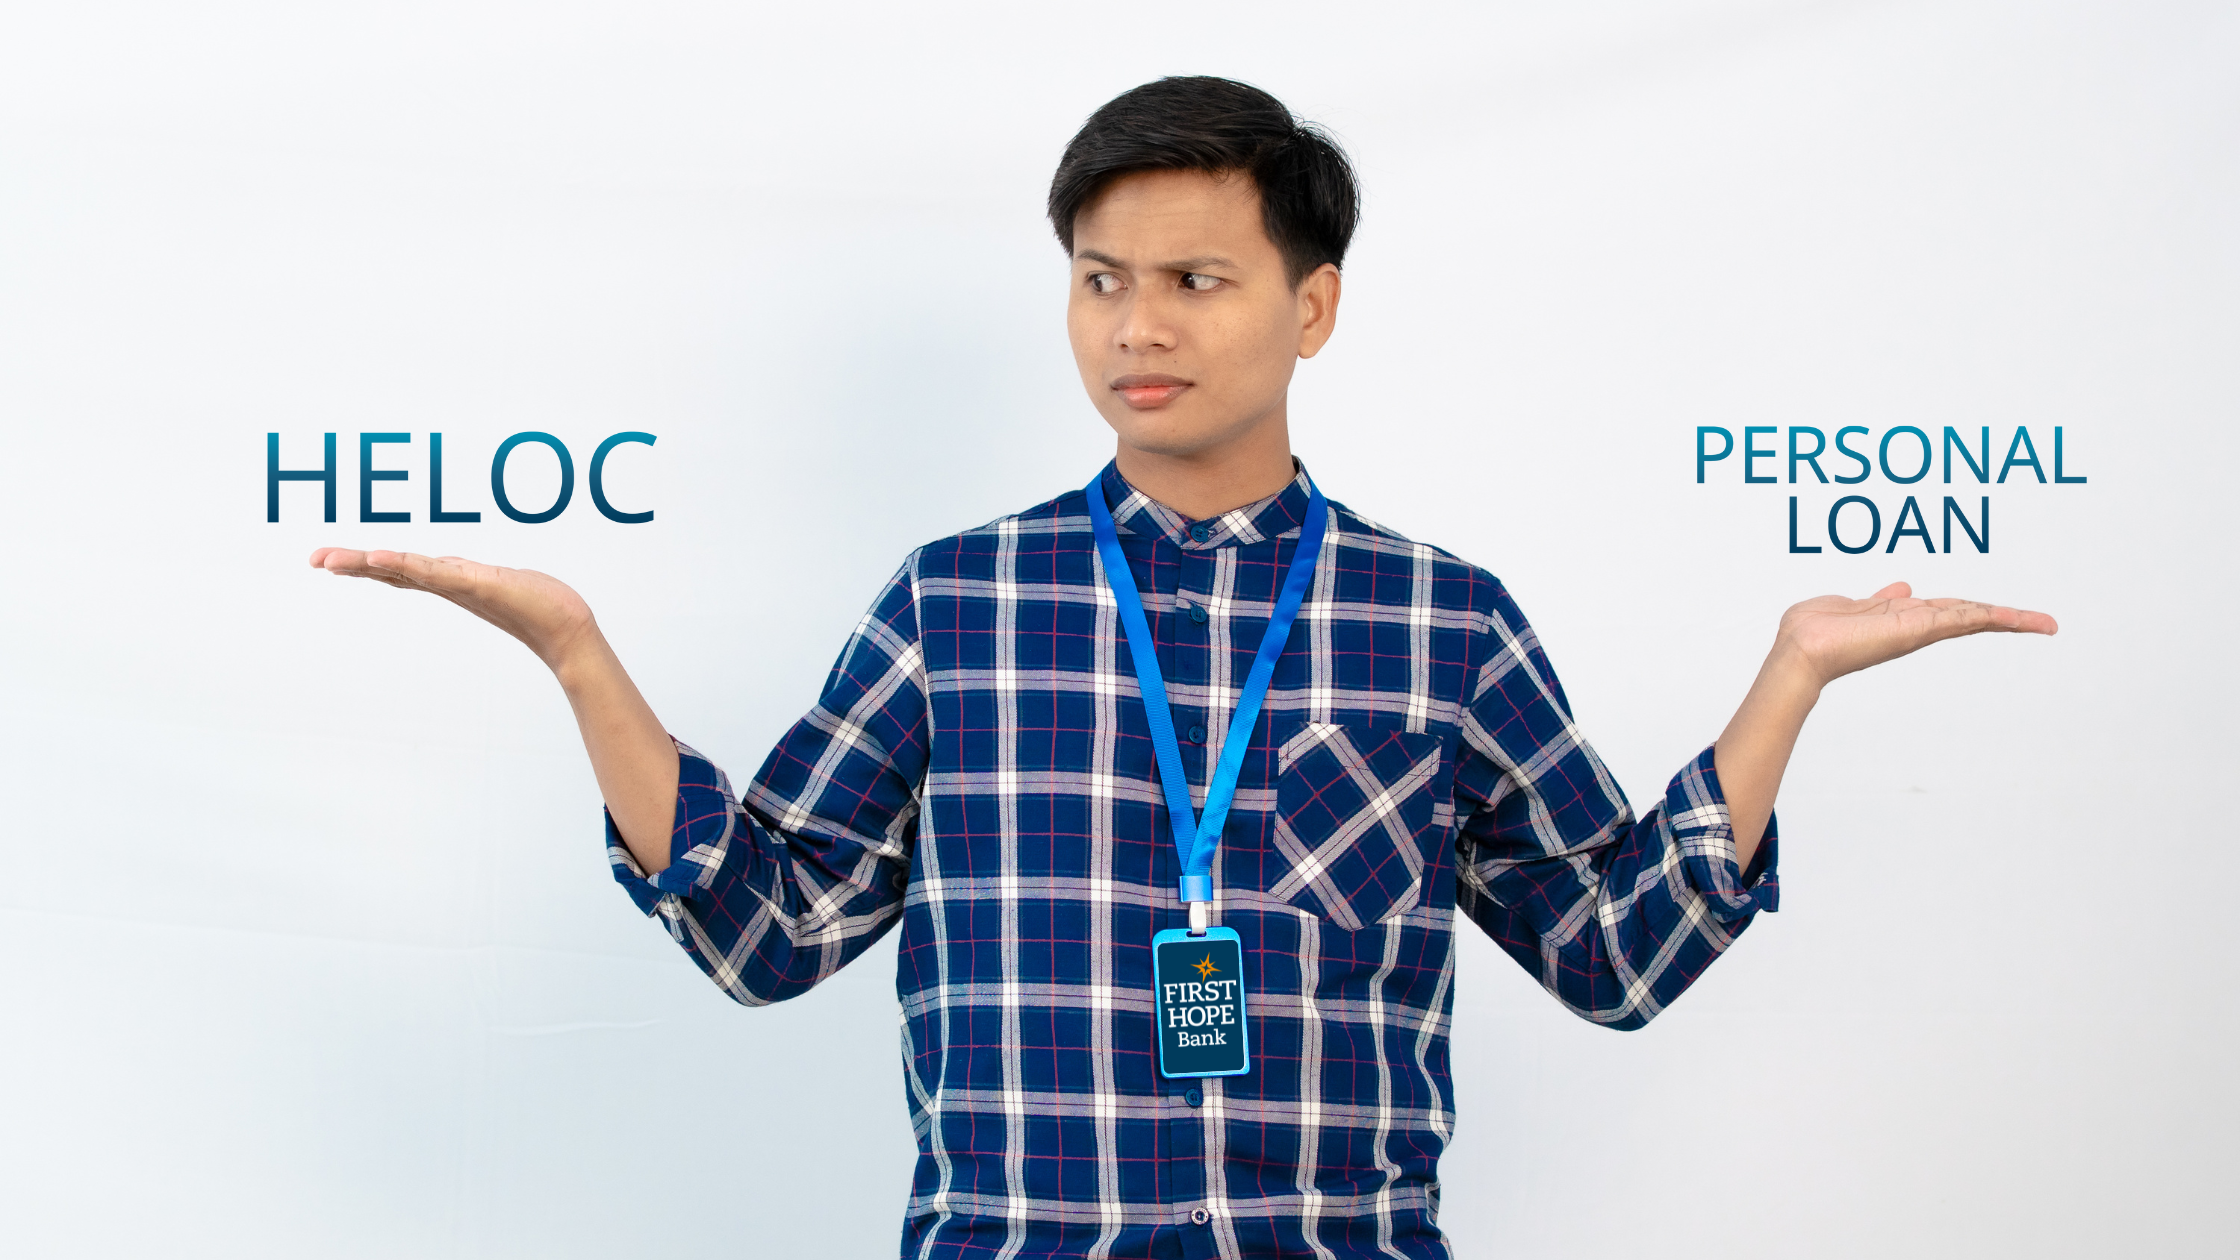
HELOC vs Personal Loan
- HELOC – Secured by your home, offers lower rates and flexible, revolving access to funds.
- Personal Loan – Unsecured, typically higher interest rates, and gives you a one-time lump sum.
If you’re comfortable using your home as collateral and want lower rates, a HELOC may be the better choice.
What Is a Line of Equity?
A line of equity is simply another term for a HELOC — the credit line you have available based on your home’s equity.
Key Takeaways
- A Home Equity Line of Credit is a flexible way to borrow for ongoing needs.
- A Home Equity Loan offers a lump sum with fixed payments — ideal for large, one-time expenses or a debt consolidation home equity loan strategy.
- Compare HELOC vs Home Equity Loan rates to decide between flexibility and predictability.
Frequently Asked Questions (FAQ)
Q: Is a HELOC tax deductible?
A: Interest on a HELOC may be tax deductible if you use the funds to buy, build, or substantially improve your home. Always consult a tax advisor for your specific situation.
Q: How much can I borrow with a HELOC?
A: Most lenders allow you to borrow up to 80–85% of your home’s appraised value minus your remaining mortgage balance.
Q: What credit score do I need for a HELOC?
A: Typically, you’ll need a credit score of 620 or higher, though higher scores may qualify you for better rates.
Q: Can I use a HELOC for debt consolidation?
A: Yes — many borrowers use a HELOC or a debt consolidation home equity loan to pay off high-interest credit card balances or personal loans.
Q: Are HELOC rates fixed or variable?
A: Most HELOCs have variable rates, though some lenders offer fixed-rate conversion options for part of your balance.